

Hello all,
Hope you all had a great weekend and got some time for rest and recovery.
Last week ended the indices only slightly higher than where we started the week on Nasdaq, The S&P however gained 125bps on the week and kept going for new highs.
This week we have the CPI and PPI data releasing and that will give the Fed further clarity into where we land when it comes to rates come next FOMC.
Realtime Discord access with equity positions tracker(new website rolling out to select subscribers), intraday orderflow & option dealer summaries included with the paid newsletter membership . Click here to subscribe.
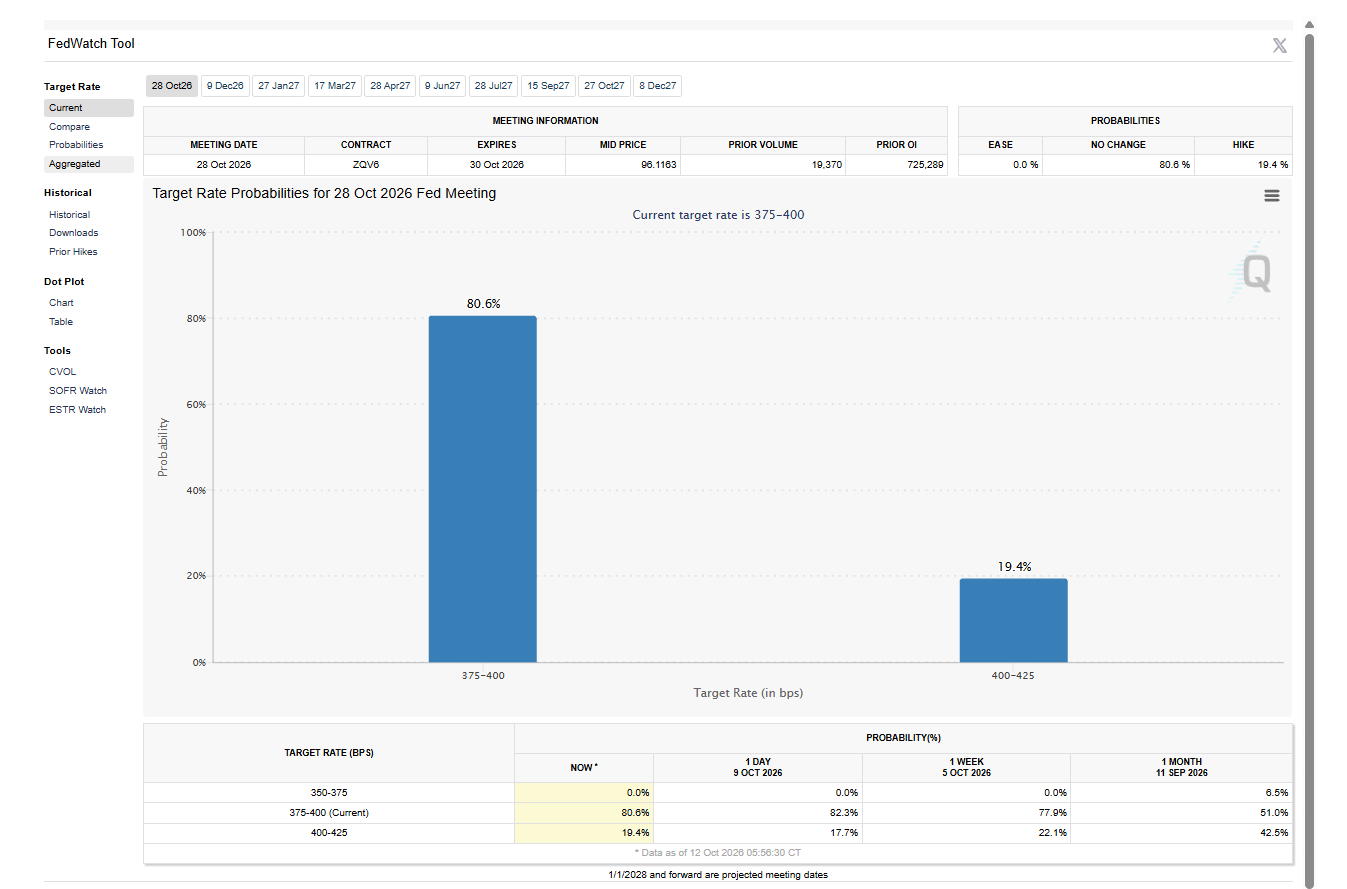
As it stands the odds are on status quo and barring a huge surprise in the CPI/PPI numbers Warsh isn’t expected to hike in this meeting.
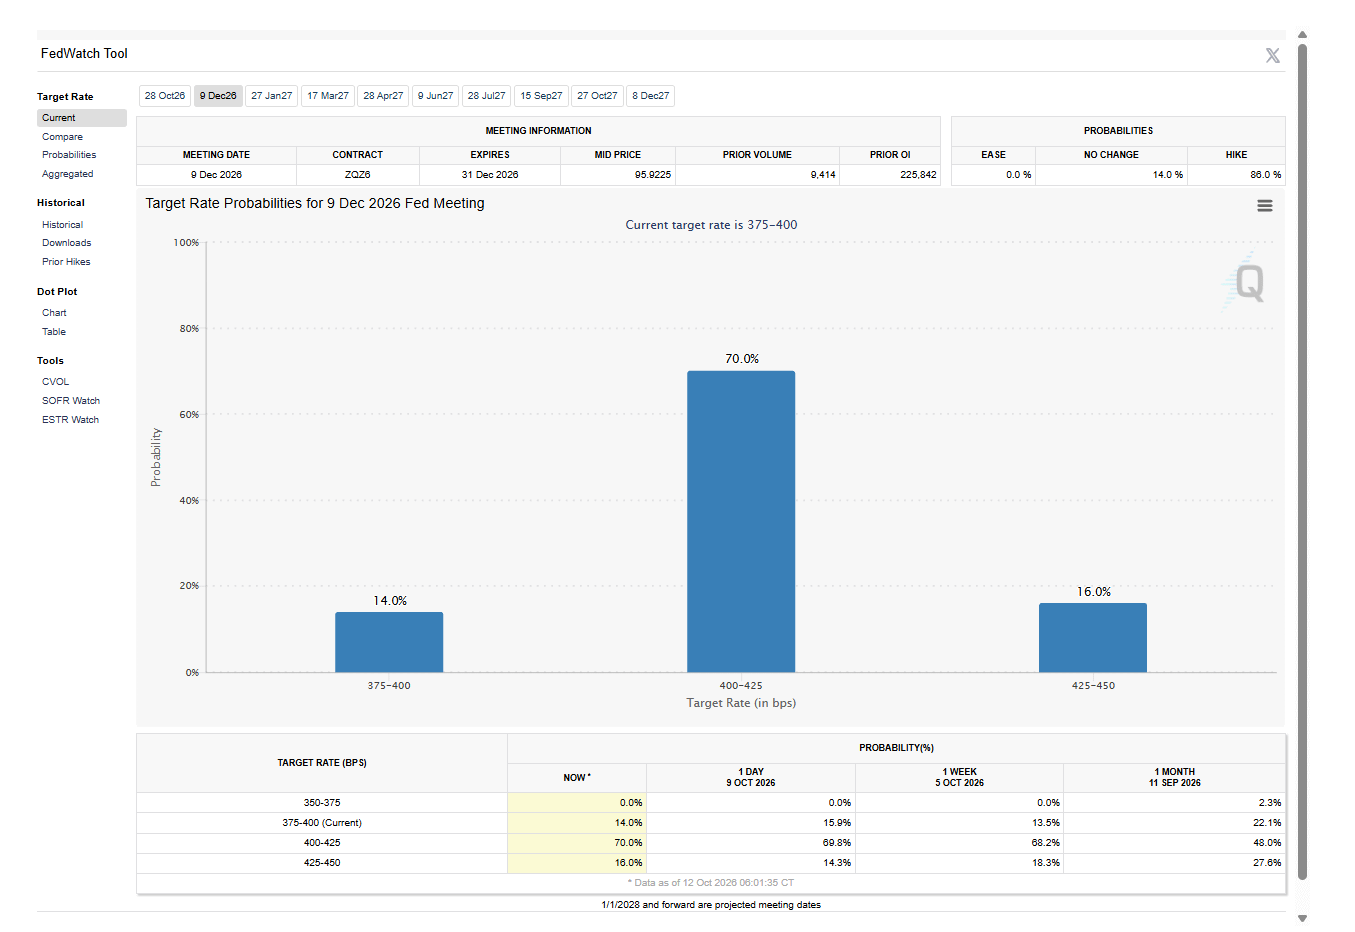
One interesting thing to note is that people who were in the two hikes before December camp are slowly thinning out and all signs are pointing towards a singular hike until EOY.
EMPEROR HAS SKIMPY CLOTHES
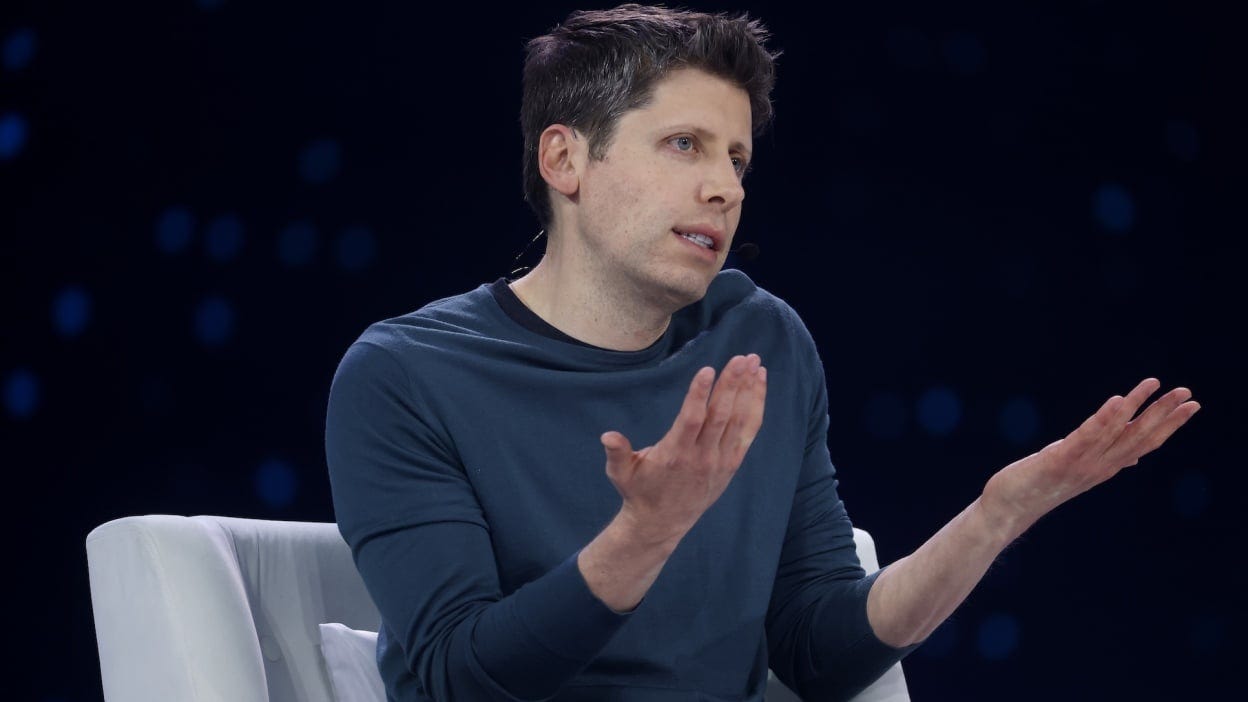
Last Thursday, news broke that OpenAI is guiding down their annual revenue forecast from $70bn to $50bn
This puts the age old question of “How skimpy are the emperor’s clothes?”
